

Equity Release
Our referral service
Explore our referral service
At Age Partnership, we believe that our business partners should be able to offer equity release as an option to their clients that have objectives that cannot be met with their current financial situation. We will talk through all of your options for clients where it may help meet their financial objectives. When you refer a client to us, our advisers will take the time to understand their circumstances, discuss the options available to them and explain the potential benefits and risks of equity release, so they can make an informed choice.
You can be assured that your clients are in good hands as we have consistently high levels of client satisfaction and access to exclusive lifetime mortgage plans.
Benefits of us working together
- Earn commission on completed referrals;
- Online case tracking;
- Our Partnership Team are on-hand to keep you up-to-date throughout your customer’s application; and
- High customer satisfaction - rated 4.6 on Trustpilot.
As well as the benefits you will receive, your clients will receive:
- Access to an award-winning service;
- An option for either over-the-phone, video call or face-to-face appointments;
- Access to exclusive plans;
- A free, no-obligation equity release quotation;
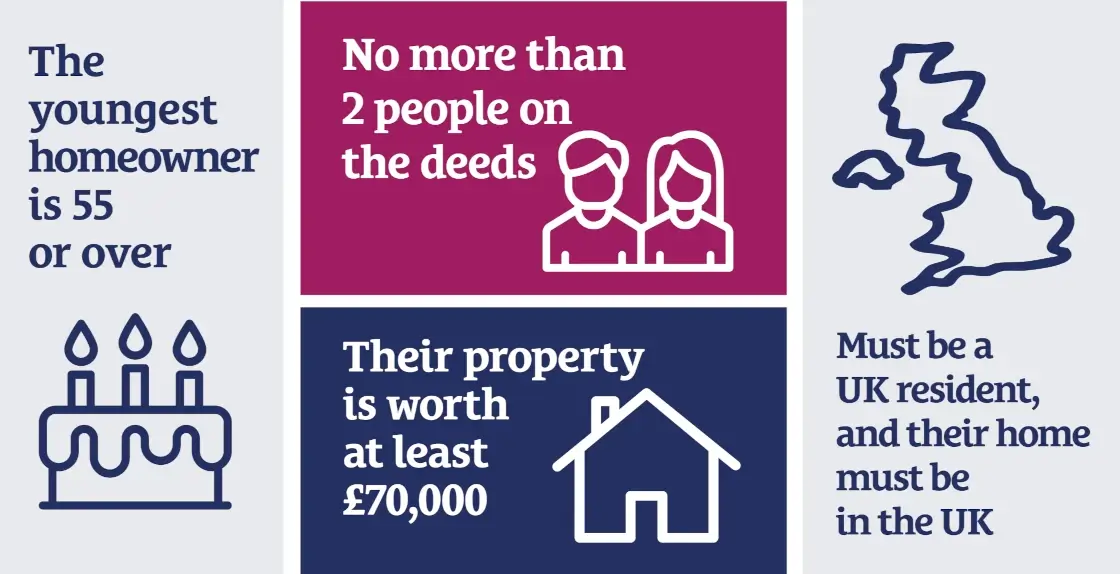
Does my client qualify?
At a minimum your client must fit the below criteria in order to be eligible for a lifetime mortgage.
How much could my client potentially release?
Property value, outstanding mortgage and the age of the youngest homeowner and client objectives will be used to calculate how much equity your client could release. In addition, lenders may also take into account health and lifestyle to maximise this amount through an enhanced plan. The minimum release amount available is typically £10,000 and any existing mortgage must be repaid.
Example case: A sole 65 year old with a property value of £300,000 and no outstanding mortgage might be able to release a maximum of £115,500 from their home.
Quote based on our panel of lenders, correct at the time of publishing (Q3 2026).
Plan Review
Regular reviews of your clients equity release plan will help to ensure that the plan still meets their needs.
Regardless of who arranged their original equity release loan we will carry out a free plan review to see if switching plans is a good option. If it’s not the right time for them to switch, we’ll tell them. Being able to change their plan will depend upon whether they qualify for the latest plan developments, the amount outstanding on their equity release plan including interest that has accrued and any potential early repayment charges that may be applicable.
Can my client release more money?
It won’t be an option for everyone but it is possible to release further money using equity release, either by using a pre-agreed reserve facility or, if they didn’t have one of those, through a further advance.
Benefits of equity release can include:
- A lump sum of tax-free cash;
- Maintaining 100% home ownership;1
- No monthly repayments to make;
- Your clients can enjoy spending the money released once any existing mortgage has been repaid; and
- Accessing a cash reserve facility.
Your client will be required to pay off any existing mortgage. Any money released, plus accrued interest would be repaid upon death, or moving into long-term care.
1 Your client only continues to own their own home with a lifetime mortgage, secured against their property.
Explore Equity Release Plans
Lifetime mortgage
A lifetime mortgage is a type of equity release that allows homeowners aged 55 or over to borrow money secured against their home while retaining ownership of it. The loan, together with any interest added, is usually repaid when the last borrower dies or moves into long-term care and the property is sold.
The amount your client could release is based on the age of the youngest homeowner, whether it is a single or joint application, the property’s value, plus recent data from our panel of lenders about the maximum amounts they may be willing to lend. In addition, lenders may also take into account health and lifestyle to maximise this amount through an enhanced plan.
Drawdown
This is similar to the standard lifetime mortgage. However, with the drawdown lifetime mortgage, you can access your money with more flexibility. Rather than just receiving a one-off lump sum, you have the option to release your cash over time, as and when you need it. Because interest is only charged on the money you have actually withdrawn, the total cost of borrowing may be lower than if the full amount were taken at the outset. The interest rate for each withdrawal is charged at the prevailing rate at the time of that withdrawal. This means that future withdrawals may have different interest rates, depending on the market rates at the time.
Interest-only
This sort of equity release plan is like a standard lifetime mortgage. However, with an interest only lifetime mortgage you can choose to make regular payments towards the interest charged on the loan. Depending on the plan, you may be able to pay some or all of the monthly interest, which can reduce or prevent interest from rolling up and help preserve more of the value of your estate.
Home reversion plans
A home reversion plan allows you to exchange the ownership of some or all of your property for a lump sum of cash, along with the right to stay in your property, rent-free, for as long as you live subject to the lenders terms and conditions. This is typically available to those who are aged 60 or over but minimum age requirements may be higher depending on the lender. Age Partnership does not advise on home reversion plans.
Other alternatives to equity release
An equity release plan is not the only option for people wishing to free up some cash in retirement. Downsizing, taking in a lodger or borrowing money from a close friend or family member are just some examples of alternatives that could be preferable to releasing equity from the home.
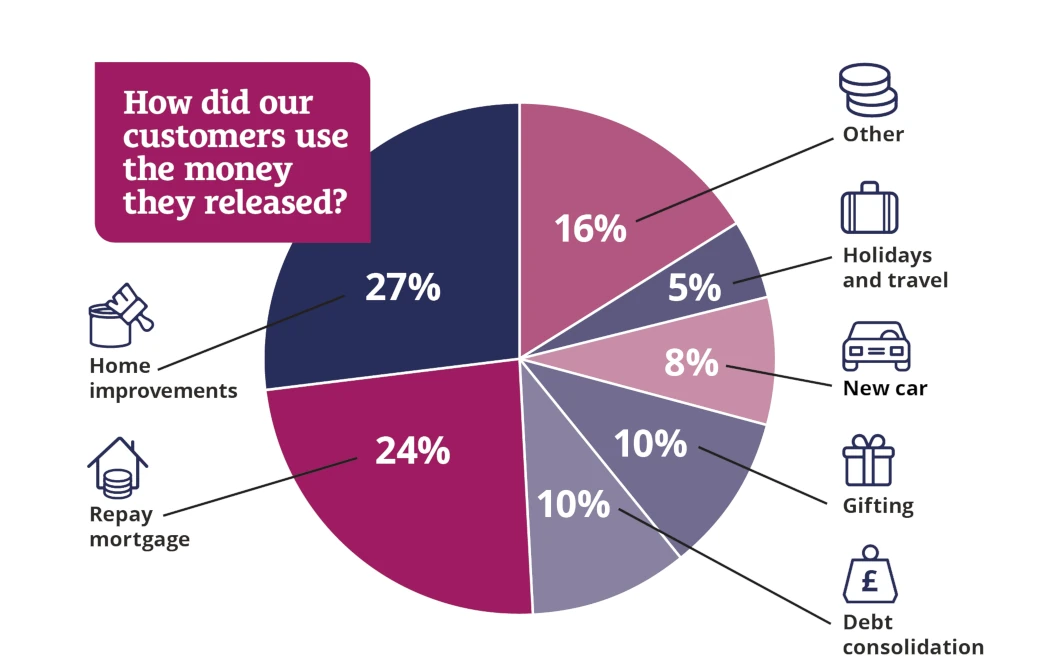
Popular reasons for releasing equity
Over recent years we have seen the majority of customers releasing money to make home improvements, provide a financial gift to loved ones and to repay their existing mortgage, which is a requirement of equity release. This chart shows how our customers used the money they released in 2025
The Referral Process
Step 1: Register as an introducer
Complete our registration and due diligence form.
Step 2: Identify a client
They must meet the minimum qualifying criteria.
Step 3: Obtain your clients consent
Ensure they are happy for us to contact them.
Step 4: Send us your referral
Referrals are accepted via phone, email or our portal.
Step 5: Updates
You will be updated throughout. Progression can also be viewed on the portal.
Step 6: Receive your referral fee
Payable at completion when all fees are received.
This part of the site is for introducers to Age Partnership and is not intended for use by the general public. If you are a customer please click here .
How do I refer my clients?
Follow these steps or contact us for more information
introducers@agepartnership.com